How to read this market report
People search for "timber prices 2026" hoping for one number per cubic metre. For hardwood that number does not exist. Oak and beech are sold in dozens of grades, diameters, thicknesses and moisture levels, and most sales are private contracts. What does exist are a few official series that show the direction of the market. We use three of them.
- Log prices: the German producer price index for logging products from state forests, published by Destatis. It is the longest public hardwood log price series in Central Europe.1,2
- Production and trade: the FAOSTAT forestry database, which collects national statistics on sawnwood output, imports and exports. Some country figures in it, including Romania's, are estimates, and we label them as such.3
- Trade values: Eurostat's Comext database of EU external and intra-EU trade by product code, which gives values and weights for 2025.5
The UNECE/FAO Forest Products Annual Market Reviews for 2024–25 and 2025–26 would normally be a fourth source. Their website blocked our automated access, so this article does not cite them. Where we use UNECE, it is the 2021–22 edition, which is mirrored by the US Forest Service.
Log prices: oak and beech since 2010
The German index measures what state forest enterprises receive for their logs, relative to 2015. It is a price index, not a price in euros per cubic metre, and it covers roundwood, not sawn timber. It is still the best public signal for the raw-material cost of a European oak or beech mill.
Show the data
| Year | Oak | Beech | Spruce (for comparison) |
|---|---|---|---|
| 2010 | 83.6 | 86.3 | 82.9 |
| 2011 | 92.8 | 94.5 | 98.1 |
| 2012 | 95.4 | 96.2 | 100.4 |
| 2013 | 95.5 | 94.9 | 100.3 |
| 2014 | 96.8 | 98.3 | 104.6 |
| 2015 | 100.0 | 100.0 | 100.0 |
| 2016 | 103.7 | 102.1 | 95.3 |
| 2017 | 107.8 | 102.2 | 96.1 |
| 2018 | 113.6 | 104.3 | 92.7 |
| 2019 | 120.2 | 103.8 | 74.4 |
| 2020 | 114.8 | 101.0 | 62.4 |
| 2021 | 116.4 | 103.1 | 79.0 |
| 2022 | 129.4 | 116.8 | 102.1 |
| 2023 | 143.1 | 133.5 | 101.6 |
| 2024 | 129.6 | 123.9 | 100.2 |
| 2025 | 129.2 | 127.5 | 111.0 |
German state forests only. An index shows direction, not price levels in euros. Source: Destatis, table 61231 (Index der Erzeugerpreise forstwirtschaftlicher Produkte aus den Staatsforsten), series Stammholz Eiche, Buche, Fichte, via DBnomics.
Three things stand out. First, oak has risen almost without pause since 2010. Its index went from 83.6 in 2010 to 120.2 in 2019, dipped in 2020 and then jumped to 143.1 in 2023. In 2025 it was 129.2, still about 29% above 2015.1 Second, beech stayed between about 95 and 104 from 2011 to 2021, then rose by almost 30% in two years, to 133.5 in 2023. It ended 2025 at 127.5.1 Third, spruce shows how differently softwood behaves. It fell to 62.4 in 2020 and recovered to 111.0 in 2025.1
Reading the German state-forest price index
The series used here is "stemwood", meaning saw logs, the part of the harvest that goes to sawmills. Destatis also publishes sub-series by quality class (A, B, C) and by diameter class. They tell a more detailed story. Grade-B oak logs reached 148.9 in 2023 and 139.9 in 2025. Grade-B oak in the thicker L5 diameter class rose further, to 167.7 in 2023, before falling back to 142.8 in 2025.1 The thick, good-quality oak logs saw the sharpest swings.
The index is German, so it says nothing directly about price levels in Romania. It is useful as a signal of direction in the Central European log market, where German, French, Romanian and Croatian mills buy the same species.
2026 so far: monthly data
Destatis also publishes the index monthly. In 2025 the oak series peaked in April at 134.7, and the beech series in October at 133.5.2 Through August 2026, oak moved sideways between about 126 and 137. Beech drifted lower and stood at 119.8 in August, after a dip to 114.1 in July.2 Spruce, by contrast, kept rising, to about 131 in July and August.2
Two monthly points do not make a trend, and monthly values swing with the mix of logs sold. The safe reading is that German hardwood log prices have come off their 2023 peak but have not returned to pre-2022 levels.
Europe's hardwood sawmilling in numbers
Higher log prices have not brought more sawing. Summing the FAOSTAT figures for the 27 EU member states gives about 10.3 million m³ of hardwood (non-coniferous) sawnwood in 2018 and about 8.6 million m³ in 2023, roughly 16% less.3 Imports and exports in this sum include trade between EU countries. Both also fell sharply in 2023.
Show the data
| Year | Production | Exports | Imports |
|---|---|---|---|
| 2015 | 9,958 thousand m³ | 5,293 thousand m³ | 3,883 thousand m³ |
| 2016 | 10,307 thousand m³ | 5,237 thousand m³ | 4,039 thousand m³ |
| 2017 | 10,192 thousand m³ | 5,820 thousand m³ | 4,275 thousand m³ |
| 2018 | 10,291 thousand m³ | 5,544 thousand m³ | 5,009 thousand m³ |
| 2019 | 10,083 thousand m³ | 5,427 thousand m³ | 5,529 thousand m³ |
| 2020 | 9,042 thousand m³ | 5,399 thousand m³ | 4,353 thousand m³ |
| 2021 | 9,703 thousand m³ | 5,996 thousand m³ | 5,090 thousand m³ |
| 2022 | 9,764 thousand m³ | 5,870 thousand m³ | 4,443 thousand m³ |
| 2023 | 8,631 thousand m³ | 4,638 thousand m³ | 3,193 thousand m³ |
Our sum of national data that mix official figures and estimates. Trade includes trade between EU countries. 2024 omitted because of a reporting anomaly for Latvia. Source: FAOSTAT, Forestry Production and Trade, bulk file Forestry_E_Europe (1 April 2026), item non-coniferous sawnwood; sum calculated by SARAL.
We stop at 2023 because the 2024 FAOSTAT sum is not comparable. One country, Latvia, reports an implausible 696 m³ of hardwood sawnwood for 2024.3 The figures are a simple sum of national data, which mix official numbers, FAO estimates and figures from industry organisations.
Who produces: Romania, France, Croatia, Germany
Four countries saw almost half of the EU's hardwood. Romania was the largest producer in the FAOSTAT data in every year from 2015 to 2023, although its figures are estimates; in 2024 France's figure was higher. All four have lost volume since 2021.3
Show the data
| Year | Romania (estimate) | France | Germany | Croatia |
|---|---|---|---|---|
| 2015 | 1,700 thousand m³ | 1,291 thousand m³ | 1,056 thousand m³ | 1,221 thousand m³ |
| 2016 | 1,700 thousand m³ | 1,488 thousand m³ | 1,088 thousand m³ | 1,214 thousand m³ |
| 2017 | 1,600 thousand m³ | 1,498 thousand m³ | 1,117 thousand m³ | 1,190 thousand m³ |
| 2018 | 1,600 thousand m³ | 1,366 thousand m³ | 1,160 thousand m³ | 1,161 thousand m³ |
| 2019 | 1,600 thousand m³ | 1,254 thousand m³ | 1,266 thousand m³ | 1,199 thousand m³ |
| 2020 | 1,615 thousand m³ | 1,133 thousand m³ | 1,002 thousand m³ | 1,042 thousand m³ |
| 2021 | 1,700 thousand m³ | 1,313 thousand m³ | 1,103 thousand m³ | 1,042 thousand m³ |
| 2022 | 1,450 thousand m³ | 1,446 thousand m³ | 1,028 thousand m³ | 1,140 thousand m³ |
| 2023 | 1,200 thousand m³ | 1,198 thousand m³ | 900 thousand m³ | 836 thousand m³ |
| 2024 | 1,100 thousand m³ | 1,198 thousand m³ | 824 thousand m³ | 923 thousand m³ |
Romania: FAO estimates and figures from industry organisations, rounded. France 2024: imputed. Germany and Croatia: mostly official. Source: FAOSTAT, Forestry Production and Trade, bulk file Forestry_E_Europe (1 April 2026), item non-coniferous sawnwood.
Germany's output, an official series, fell from 1.27 million m³ in 2019 to 0.82 million m³ in 2024. Croatia fell from 1.20 to 0.92 million m³ over the same period. France held at about 1.2 million m³ in 2023–2024, though its 2024 value is imputed.3 The survey of the European sawmill and timber trade federations (EOS/ETTF), covering eleven countries, shows the same picture: about 5.9 million m³ in 2023 and a forecast of 5.7 million m³ for 2024.6
What has been squeezing sawmills
The UNECE/FAO review of 2021–22 named the pressures that still apply. Rising electricity costs were "a big challenge" for European hardwood sawmills. Beech in Central Europe suffered in the hot, dry summers of 2018–2020 and 2022, with many trees dead, dying or weakened. And international competition for raw material was driving exports of mostly unprocessed oak logs, primarily to China.7 Small and medium sawmills suffered most. A study cited in the same review found that about 26% of hardwood sawmills in Wallonia, Belgium, closed between 2010 and 2020.7
The China factor: beech and oak logs leave Europe
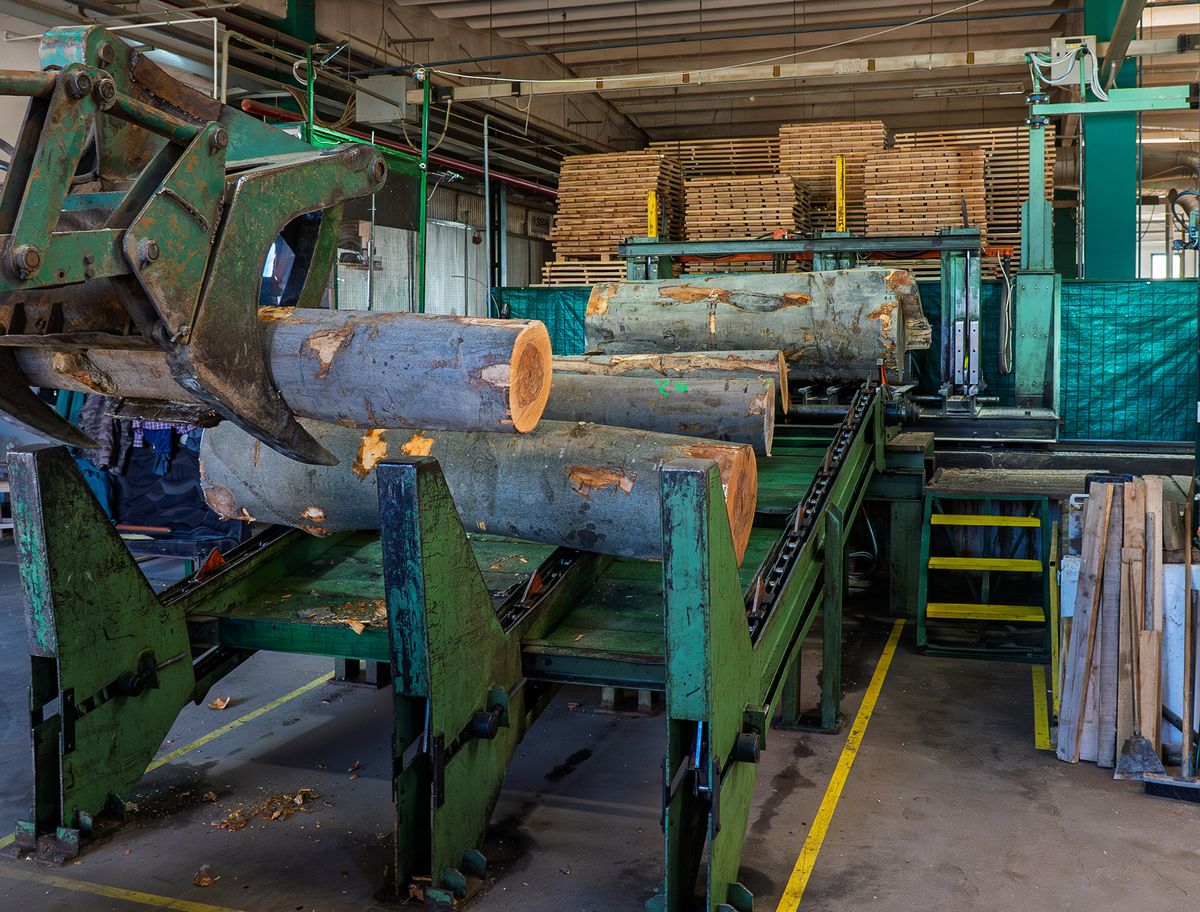
Chinese buyers have been the marginal bidders for European hardwood logs for a decade. In 2021 Chinese imports of European oak logs rose by more than 25% to over 700,000 m³, and China also took 29% of Europe's sawn hardwood exports, about 950,000 m³.7 In early 2022 Russia banned log exports. Russia had supplied slightly less than a fifth of China's oak-log imports, and European logs filled the gap. Bosnia and Herzegovina, Croatia and Serbia responded with temporary 60–90-day export bans on some wood products, including oak logs.7
Beech follows the same pattern. Germany exported 626,000 m³ of beech logs in 2024, of which 274,000 m³ went to China.8 China imported 555,000 m³ of beech logs in the first ten months of 2025, about the same as a year earlier. Germany supplied 241,300 m³ and France 93,400 m³, while Slovakia's deliveries more than doubled to 61,100 m³.4
Romania hardly appears in these flows. FAOSTAT records Romanian exports of hardwood industrial roundwood at about 22,000 m³ in 2024, against about 1.01 million m³ from Germany and 1.84 million m³ from France.3 Romanian beech and oak are sawn and processed in Romania.
Sanctions on Russia and Belarus: what disappeared from the market
Since 2022 the EU has banned imports of wood and wood products of chapter 44 from Russia, with existing contracts allowed to run until 10 July 2022.9 An equivalent ban on wood products from Belarus was adopted on 2 March 2022, with existing contracts allowed to run until 4 June 2022.10 FAOSTAT shows the effect on hardwood. Belarus's exports of hardwood sawnwood fell from 428,000 m³ in 2021 to about 2,000 m³ in 2023. Russia's fell from 1.99 million m³ in 2021 to 1.12 million m³ in 2024.3
Under the EUDR's country benchmarking, both countries are classed as high risk, the strictest category. The sanctions keep their wood out of the EU in any case. Our EUDR guide explains what the regulation, which applies from 30 December 2026, means for buyers.
Romania: large producer, home processing, falling output
Romania's hardwood sawnwood output in FAOSTAT falls from about 1.7 million m³ in 2015 and 2021 to about 1.1 million m³ in 2024. These are FAO estimates and figures supplied by industry organisations, not official statistics, so treat them as approximate.3 They match the Romanian figures in the EOS/ETTF survey of 2024: 1.1 million m³ produced and 500,000–600,000 m³ exported in 2023–2024, with 2024 shown as a forecast.6
ASFOR, the association of Romanian forestry and wood companies, writing in that survey, linked the decline to a lower harvest in 2023 and "relatively high prices of the primary wood resource". It also cited weaker export demand and lower domestic demand for firewood.6 Official exports of hardwood sawnwood fell from 806,000 m³ in 2015 to 461,000 m³ in 2022. Estimates for 2023–2024 put them at 500,000–600,000 m³.3
Eurostat trade data for 2025 add detail by species. They are in euros and tonnes, not cubic metres.
| Species (HS code) | Value 2019, € m | Value 2025, € m | Weight 2019, thousand t | Weight 2025, thousand t | € per t 2019 | € per t 2025 |
|---|---|---|---|---|---|---|
| Beech (4407 92) | 142.6 | 109.0 | 344.0 | 202.6 | 415 | 538 |
| Oak (4407 91) | 27.0 | 52.5 | 32.8 | 80.5 | 822 | 652 |
| Ash (4407 95) | 3.8 | 6.1 | 4.6 | 6.2 | 836 | 983 |
Weights are in tonnes, not cubic metres. A value per tonne averages all grades, thicknesses and drying states, so it is not a price list. Source: Eurostat, Comext DS-045409, reporter Romania, partner world, exports, queried 23 October 2026. Value per tonne = value divided by weight, calculated by SARAL.
Romania exported less beech by weight in 2025 than in 2019, but the average value per tonne rose by about 30%. Oak exports more than doubled by weight, while their value per tonne fell. That usually means a different mix of grades and products, not cheaper oak.5 An export unit value averages everything from pallet boards to kiln-dried furniture grades, so it is not a price list. For how wood moves from forest to sawmill in Romania, see Romania's hardwood forests in numbers.
What a sawn-timber quote is made of
Romania has no public price index for sawn oak or beech; we found no official series from the national statistics institute. Quoted prices online ("preț m³ cherestea stejar") mix grades, thicknesses and fresh-sawn with kiln-dried timber, so they are hard to compare. A quote is built from a few cost blocks that buyers can check.
- The log. Grade and diameter drive the log price, as the German sub-indices show. Large clear oak logs have risen fastest.1
- Yield. A sawmill turns only part of each log into saleable boards, and only part of those boards into the clear grades furniture needs. Our guide to hardwood lumber grades explains how grade sets the yield of usable pieces.
- Drying. Kiln drying is the most energy-intensive step of sawnwood production. See our article on kiln drying hardwood for energy per cubic metre and drying times.
- Processing. Optimising, edging, planing and gluing turn sawn boards into parts. Each step costs money and also removes the defects you would otherwise pay to cut out yourself.
- Documentation. From 30 December 2026, wood placed on the EU market needs EUDR documentation behind it. A supplier who can hand over reference numbers saves the buyer work.
What it means for buyers in 2026
Three practical conclusions follow from the data. They are our reading of the data, not forecasts.
- Raw material is unlikely to get cheap. Even after the 2024 correction, oak and beech log indices in 2025 were 27–29% above 2015, and 2026 monthly values have stayed in a range.1,2
- Capacity is thinner. European hardwood sawnwood output was about a sixth lower in 2023 than in 2018.3 Fewer mills means fewer alternatives when one supplier is full.
- Origin and documentation matter more. Sanctions removed Russian and Belarusian wood, and the EUDR adds a documentation requirement for all wood placed on the EU market from 30 December 2026.9,10
For a buyer, that argues for fewer, closer suppliers who control more of the chain from log to part, and for specifications that ask for the grade a part needs rather than the best grade available.
How we buy and process at SARAL
How to compare hardwood quotes
- Same grade, same rules. Ask which grading rules the quote uses, for example EN 975-1 for oak and beech or NHLA for American timber, and which grade.
- Same moisture. Fresh-sawn, air-dried and kiln-dried timber are different products. Ask for the target moisture content and tolerance.
- Same measure. Ask whether volume is measured fresh or dry, nominal or net, and whether unedged boards are measured at mid-width.
- Same documents. Ask what EUDR information comes with the delivery and who the operator is.
- Price validity and indexing. In a volatile log market, ask how long the price holds and whether it is tied to an index.
Frequently asked questions
Why are oak prices so high?
Because oak logs became scarcer and more contested. The German oak stemwood index rose from 100 in 2015 to 143.1 in 2023, driven by strong demand, export of logs to China and, from 2022, the loss of Russian supply to China. It was still 129.2 in 2025.1,7
What is the price of oak per m³?
It depends on grade, diameter, thickness and moisture, so any single number misleads. Official sources publish indices rather than euro prices. Compare quotes for the same grade, the same moisture and the same way of measuring volume.
Will timber prices fall in 2026?
Up to August 2026, German hardwood log prices were below their 2023 peak but well above 2015. Oak moved sideways and beech eased slightly, while spruce rose.2 We do not make forecasts.
How much hardwood lumber does Romania produce?
About 1.1 million m³ of hardwood sawnwood in 2024 according to FAOSTAT and the EOS/ETTF survey, of which roughly 500,000–600,000 m³ was exported. Both figures are estimates.3,6